Mudra Loan Business Plan Generator: Free AI DPR for Shishu, Kishor & Tarun (PMMY)
What a Mudra Loan Business Plan Actually Is
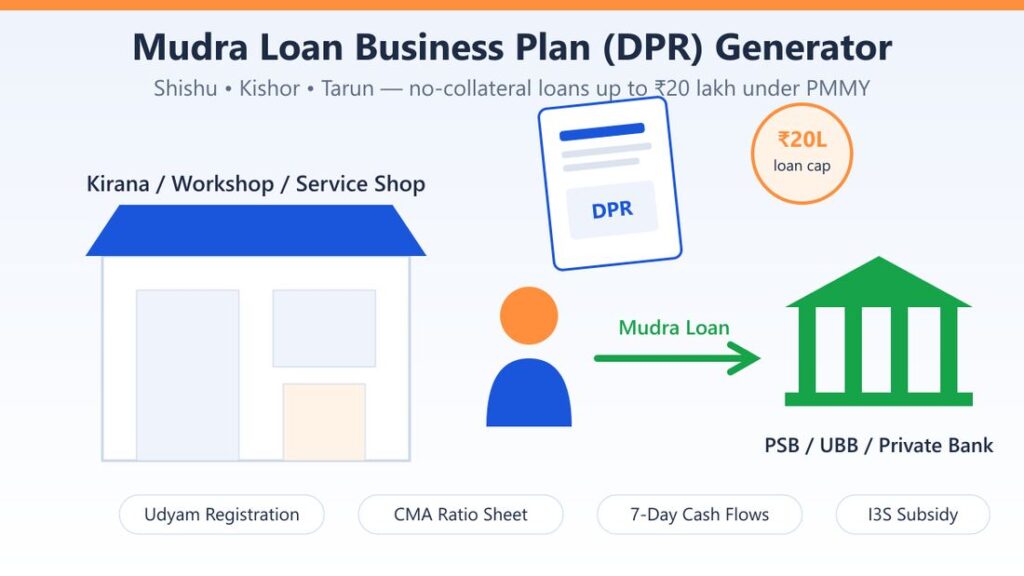
A mudra loan business plan generator exists because this document is not a “business plan” in the startup-pitch sense. In other words, under the Pradhan Mantri MUDRA Yojana, the paper a bank’s credit officer assesses is a Detailed Project Report (DPR): project cost, means of finance, promoter contribution, 3–5 year projections, CMA data, and a scheme-fit statement proving you qualify for Shishu, Kishor or Tarun. Miss one of those and the file does not move past the branch, no matter how good the idea is.
MUDRA stands for Micro Units Development & Refinance Agency — the Government of India refinance facility for micro enterprises. Loans are collateral-free, sanctioned through banks, NBFCs and MFIs, up to ₹20 lakh per borrower across the three categories. PMMY remains one of the highest-volume credit schemes in India, and the DPR is its gatekeeper. A dedicated mudra loan business plan generator builds to that DPR structure rather than a generic template.
Shishu, Kishor or Tarun: Which Category Is Yours?
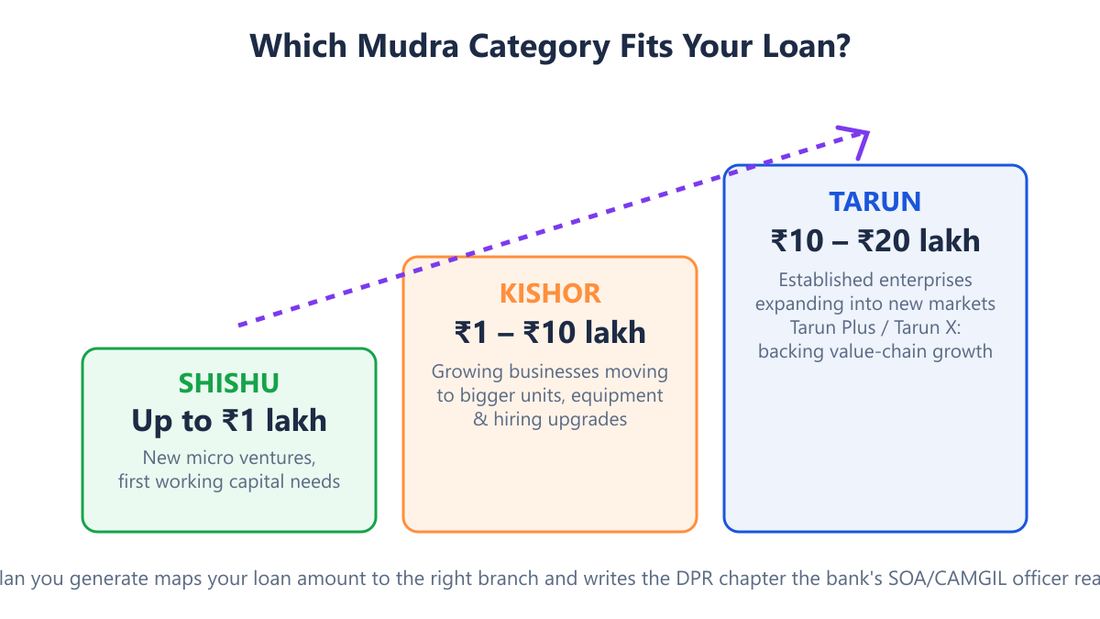
| Category | Loan range | Typical borrower | What the DPR must prove |
|---|---|---|---|
| Shishu | Up to ₹1 lakh | First venture, street/cart trade, home-based unit | Basic project cost + promoter identity; viability of a small, concrete money cycle |
| Kishor | ₹1 – ₹10 lakh | Running business adding equipment, a second outlet, or staff | Existing bank-statement history or proven trading cycle; repayment capacity from incremental cash flow |
| Tarun | ₹10 – ₹20 lakh | Established micro enterprise expanding markets or value chain | Full financial track record, DSCR above ~2.0, utilization statement for prior loans |
Two details most template sites get wrong: the ₹20 lakh ceiling applies to your aggregate MUDRA exposure across all categories and lenders, and Tarun Plus/Tarun X variants extend support for value-chain and larger expansion financing under the updated scheme architecture. If you have drawn a MUDRA loan before, the new application must show clean utilization — the bank will ask.
The 9 Chapters an Indian Bank Expects in a MUDRA DPR
- Promoter profile — age, education, experience in this exact trade, prior loans, CIBIL note
- Project description — what you sell, to whom, at what price, in which locality
- Project cost — itemised: machinery, interiors, initial stock, deposits, margin money
- Means of finance — promoter contribution (typically 10–15% for MUDRA), loan asked, any subsidy
- Market analysis — catchment, competition, pricing evidence (not claims)
- Operating plan — timings, staff, supply chain, GST/Udyam status
- Financial projections — 3 years: P&L, balance sheet, cash flow, broken-periodity for the first year
- CMA data sheet — the ratio table technical officers benchmark your unit against
- Annexures — Aadhaar, quotations/proforma invoices, rent proof, Udyam certificate, photographs
How This Mudra Loan Business Plan Generator Works
BizPlan AI Pro’s mudra loan business plan generator inverts the usual order — numbers first, prose second:
- Answer 15–20 India-specific questions: business type, city and state, Shishu/Kishor/Tarun target, loan amount, promoter contribution available, GST status, existing Udyam registration.
- The finance engine builds the DPR maths: project cost from your item list, month-wise projections, working-capital cycle, DSCR and break-even. You see the ratios the bank will see.
- AI writes the narrative chapters around the validated numbers — in English, Hindi, or both — in the wording branch staff are used to reading.
- Bankability gate: if the loan ask is unrealistic for your category, contribution is too thin, or DSCR fails, export locks and the tool tells you exactly which input to fix. Nothing goes to a bank counter that cannot survive appraisal.
- Export the DPR PDF with the CMA sheet and chapter order matching PMMY assessment practice.
Why MUDRA Applications Get Rejected
- Copy-paste project reports from generic templates — same margins, same machinery prices for every shop in the district. Technical officers spot these instantly.
- Projected turnover that contradicts the loan size. Asking ₹8 lakh against a shop that visibly clears ₹40,000/month fails the common-sense test before the maths even starts.
- No promoter contribution evidence. “100% loan required” is a red flag; the scheme expects skin in the game.
- Wrong category. A ₹12 lakh ask filed as Kishor instead of Tarun bounces at sanction level.
- Missing utilization proof from a previous MUDRA loan.
Every one of these is a document-quality failure, not a business-quality failure. Consequently, this mudra loan business plan generator gates the export until each is resolved.
Interest Subsidy, Timelines and Ground Rules
Interest rate: bank-priced; the 7% ceiling on MUDRA interest was announced for priority-sector lending and actual pricing varies by lender and profile. Processing: sanction typically 1–3 weeks for complete files; MUDRA is a scheme, not a guaranteed approval. Subsidy: eligible first-time borrowers under PMMY can claim the I3S upfront interest subsidy (up to 3% per annum on eligible loans) through the lender — ask your branch to mark the file. PSB MUDRA camps: participating banks run periodic camps where decisions happen in days, not weeks — a complete DPR is what lets you use them.
FAQs
Can I apply for a MUDRA loan without GST registration?
Yes. Many Shishu and Kishor borrowers are below the GST threshold. The DPR should state this honestly and show the turnover projection that keeps you there — or the plan to register as you cross it.
Is Udyam registration required?
Not legally required for the loan, but it takes one free online session and materially strengthens the file — several lenders pre-screen on it. The generator includes a Udyam-readiness section.
Can the same plan be used at multiple banks?
Yes — apply where the branch relationship exists (your savings/current bank first). One validated DPR, N branches. You cannot draw two MUDRA loans above the aggregate ₹20 lakh cap.
Does the bank check CIBIL for MUDRA?
Practice varies; many branches do a credit bureau check even though MUDRA is collateral-free. A DPR cannot fix a bad bureau score, but it can present repayment capacity so strongly that borderline files still get a fair technical hearing.
Related Tools
Comparing routes? See the DPIIT startup plan generator if you are innovation-led rather than micro-enterprise-led, the Hindi plan generator for a bilingual submission, and the free India business plan template for the manual build. The tool itself lives on our business plan generator for India homepage, and how we scored every tool in the SERP is here: best business plan generator for India.

The BizPlan AI Editorial Team comprises startup consultants, financial analysts, and professional technical writers. We compile verified Indian market data and MSME guidelines to help entrepreneurs build investor-ready business plans.